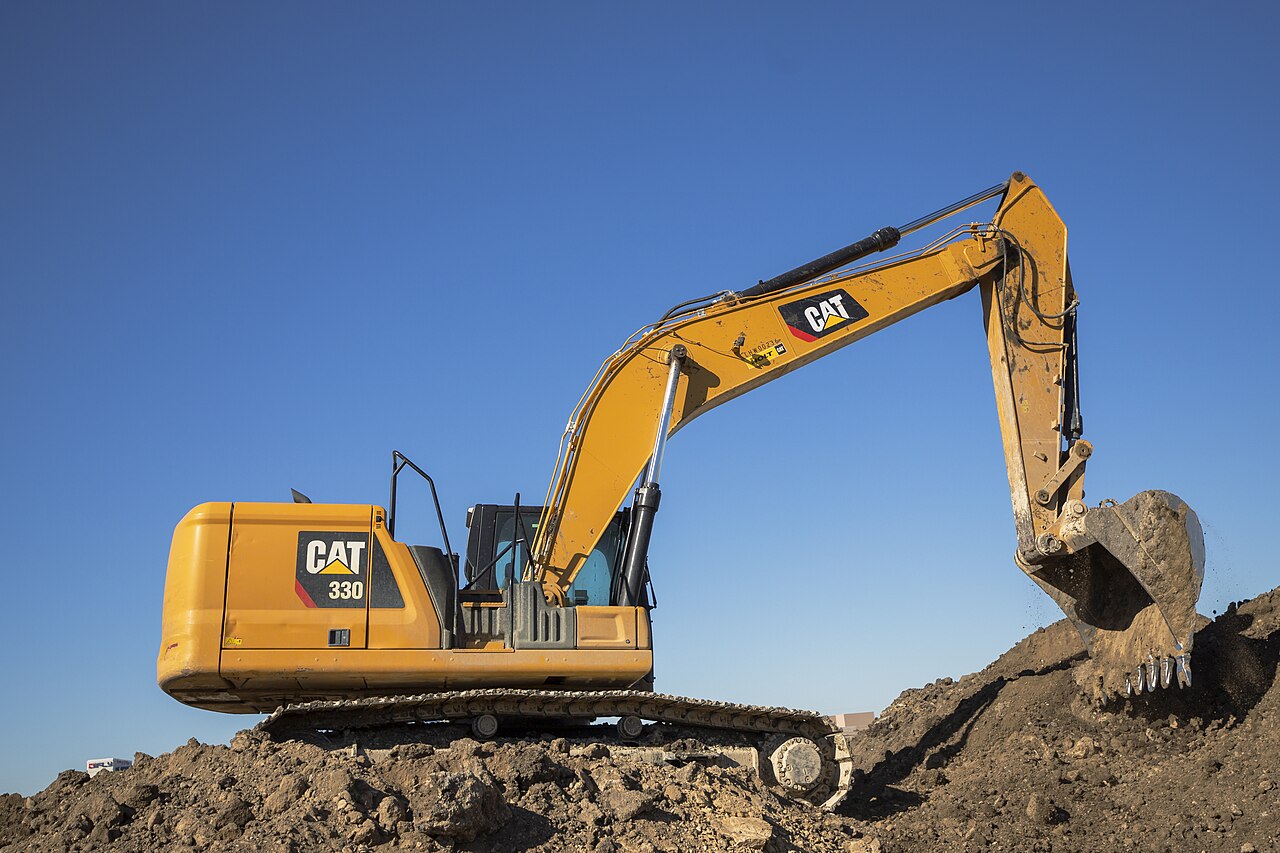

Illustrative equipment photo: a Caterpillar 330 excavator. Not an EquipEASE-financed machine or local customer job. Photo: Matthew T Rader, MatthewTRader.com, “Caterpillar 330 excavator on a pile of dirt”, Wikimedia Commons, CC BY-SA 4.0..
Licence: CC BY-SA 4.0.
What should a newer Okanagan business prepare for an equipment-finance enquiry? Start with a short business summary, the equipment and seller details, an approximate purchase price, how the equipment will be used, and your preferred timing. That gives a broker a useful starting point before asking you for a full application.
Sponsored member guide: EquipEASE Lease Co is a paying Okanagan Trade Directory member. Originally published September 22, 2026; this existing guide was updated October 21, 2026. This is general enquiry preparation, not an approval, rate quote or individual financial recommendation.
Talk to EquipEASE: Start on EquipEASE’s website, email info@equipease.ca, or call 1-844-250-3273. Use the directory contact buttons to call or email directly. Ask for Kyle and mention the equipment you are considering.
Can a new business get equipment financing?
Time in business is one part of an assessment. The equipment, business finances, proposed use and lender’s criteria also matter. A useful first question is whether the provider considers businesses at your stage, before you spend time completing an application.
Requirements differ between products. For example, BDC’s equipment-loan page currently lists at least 12 months generating revenue among its general requirements. Separately, the federal Canada Small Business Financing Program includes eligible Canadian start-ups and can support new or used equipment through participating financial institutions. The lender makes the credit decision. These examples are not EquipEASE eligibility rules or a claim that EquipEASE administers that program.
For startup equipment financing or leasing, ask Kyle which options may fit your business stage and the specific asset. An enquiry does not establish eligibility or commit you to a financing agreement.
Your first-enquiry checklist
You can begin with the following ordinary business and equipment information. If a figure is not known yet, say so.
- Business: Trading name, town and when you started operating. Identify whether this is a new venture, an owner-operator business or an established company adding equipment.
- Equipment: Type, make, model and year, if selected. For a used asset, note available hours or mileage and the seller’s description of condition.
- Seller and price: Dealer or private seller, quote or listing link, approximate price. Say which taxes, delivery, installation or attachments are included in the quoted amount.
- Intended use: The work the equipment will perform. Explain how it supports existing work, a new service or a proposed contract. Distinguish confirmed work from forecasts.
- Timing: Desired purchase and delivery dates. Mention any expiry date on the seller’s quote; do not assume funding can meet it.
- Business stage: What operating history you have. Ask which business records and projections the relevant lender would require.
- Structure: Whether you are comparing a loan, lease or both. Ask about ownership and the end-of-term purchase option.
- Contact: Name, callback number and preferred time. Include a few questions you want answered before applying.
Keep the first email brief. Ask for the appropriate secure application method before sending identity documents, bank statements or other sensitive records. A public directory enquiry is not a place to upload a complete financial file.
Buying a first truck, excavator or another machine
An equipment-specific enquiry is easier to discuss than “I need financing.” A new owner-operator considering a dump truck can identify the truck’s year, model, mileage, seller, purchase price and intended work. A contractor considering an excavator can identify its year, hours, condition and included attachments.
For a boom lift, bulldozer or other construction machine, use the same approach: identify the asset, its intended job and the seller’s quote, then ask whether that asset and business stage fit the available financing options. These are enquiry examples, not promises that any particular machine or applicant will be approved.
EquipEASE’s website describes construction and heavy-equipment financing, transportation and trucking, agriculture, medical and dental equipment, and other business sectors. Confirm the specific equipment with Kyle rather than assume that a broad industry description covers every purchase.
Planning a specific construction-equipment purchase in Canada
The first-enquiry checklist also helps Canadian businesses describe the asset they intend to buy. A machine-specific question is more useful than a general request for an approval rate: give the exact equipment, seller, price, business stage and purchase timing. Ask which options can be considered for your province and transaction.
- Buying an excavator or mini excavator? Read the Canadian excavator financing and leasing guide for questions about hours, used machines, attachments and seller deadlines.
- Comparing a wheeled skid steer with a compact track loader? Read the Canadian skid-steer financing and leasing guide for equipment identification, purchase packages and startup enquiries.
For another asset, such as a dump truck, boom lift or bulldozer, identify the proposed machine and ask Kyle whether that purchase can be considered. These examples do not establish approval or identical lending rules across every equipment type or Canadian jurisdiction.
Questions to ask before a formal application
- Do you consider businesses at my stage, and which equipment types can you assess?
- What documents are needed now, and what can wait until a suitable option has been identified?
- Is the discussion an initial enquiry or a formal credit application? When would a credit check occur, and what consent is needed?
- What upfront payment, fees, security or personal guarantee could apply to the proposed option?
- How are the payment amount, term and any end-of-term purchase option shown in the written proposal?
- What happens if I need to pay out early, replace the machine or sell the business?
- Which conditions must be satisfied before funds can be released to the seller?
Ask for the actual written terms. Monthly payment, interest rate, fees and any final payment are different parts of the comparison. Your accountant or legal adviser can help assess tax treatment, guarantees and the contract’s effect on your business.
A simple first-email example
Hi Kyle, I run a business in [town] and have been operating since [month/year]. I’m considering a [equipment type, year and model] from [seller] for approximately [price]. It would be used for [work]. I’m aiming to purchase around [date]. Do you consider businesses at my stage, and what information would you need to discuss suitable financing or leasing options? My preferred callback number/time is [details].
Use your real facts and leave out anything you have not confirmed. You do not need to attach sensitive documents to ask this first question.
Frequently asked questions
What if my business has less than two years of financial history?
Describe the history you do have and ask which products consider that stage. Do not assume that all banks require two years, that all start-ups qualify, or that a broker’s enquiry is a credit approval.
Can I ask about used equipment or a private-sale machine?
Yes, you can ask whether the proposed purchase can be considered. Give the seller type and available equipment details. Ask what title, condition, inspection or valuation checks would be needed for that particular transaction.
Does sending an enquiry affect my credit?
An email asking what information is needed is different from submitting a credit application. Ask the provider to explain any credit check and consent before proceeding. This guide does not describe the credit-check policy of every form or financing product.
Should I lease or finance the equipment?
Ask for a comparison that reflects how long you plan to use the asset, ownership at the end, the full payment schedule and any purchase option. The right choice depends on the specific proposal and your business circumstances.
Continue with the relevant guide
- Buying a used machine? Read used-equipment financing in Kelowna.
- Comparing structures? Read equipment leasing versus financing.
- Preparing an application? Read the existing equipment-finance application guide, then confirm the actual lender’s requirements.
Contact Kyle at EquipEASE
Bring the short checklist above to your first conversation. Visit EquipEASE, email info@equipease.ca, or call 1-844-250-3273. You can also view the EquipEASE directory profile.
Sources checked October 21, 2026: EquipEASE’s official website, BDC’s equipment-loan requirements, and the Canada Small Business Financing Program’s borrower information. Program rules and financing terms can change; confirm the relevant provider’s current requirements.